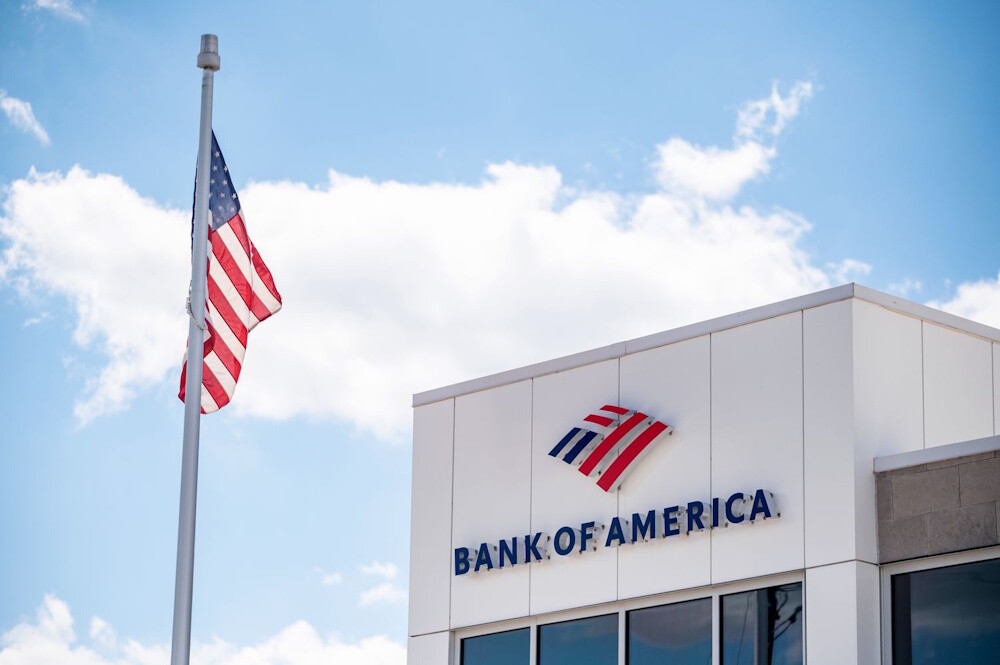
The US Treasury Department on Tuesday announced it was imposing a fine exceeding $1.2 billion on Bank of America, citing violations of anti-money laundering and sanctions laws by the bank. The bank, recognised as the second-largest in the US, did not adequately address or disclose “priority national security risks, including Chinese Money Laundering Networks and illicit finance along the southwest border,” according to the Treasury Department’s announcement. “When a bank of this size fails to meet its anti-money laundering and sanctions obligations, the consequences extend far beyond its own walls, exposing the entire U.S. financial system to significant illicit finance risks,” said Treasury Secretary Scott Bessent in a statement. “Today’s actions send a clear message that even the biggest financial institution[s] are not above the law,” Bessent added. In a statement, Bank of America indicated that it was collaborating with regulators to achieve resolutions regarding penalties. “We have invested billions of dollars in technology and dedicated thousands of employees to combat financial crime, and our team is far along with and committed to completing the work required to address the issues raised by our regulators,” a Bank of America spokesperson said. “We will continue to support federal and local law enforcement across thousands of investigations and report hundreds of thousands of suspicious activity reports each year.”
The spokesperson also indicated that the penalty imposed by the Treasury Department will affect the company’s quarterly earnings results, which are anticipated to be disclosed on Wednesday. “Our third-quarter results will include a non-tax-deductible charge of $1.2 billion impacting net income by approximately 17 cents per share. We have already dedicated substantial personnel and resources to our ongoing remediation efforts, and those costs are in the current expense base,” the spokesperson said. The 1.2 billion dollar fine represents the third-largest penalty ever levied by the Treasury Department’s Financial Crimes Enforcement Network, trailing only the unprecedented 3.4 billion dollar fine against Binance in 2023 and the 1.3 billion dollar penalty imposed on TD Bank in 2024. Both fines were accompanied by charges from the Justice Department; however, there is no corresponding Justice Department action for the Bank of America fine. The second Trump administration has implemented measures targeting large financial institutions for the practice of “debanking,” including through executive orders. Earlier this year, President Donald Trump filed a $5 billion personal lawsuit against JPMorgan Chase, alleging that the country’s largest bank closed his account for political reasons. However, the fine against Bank of America represents the largest anti-money-laundering penalty imposed by the Treasury Department during the Trump administration on a major financial institution.
As part of the total fine, $750 million will be allocated to the Office of the Comptroller of the Currency as a civil penalty, marking it as the largest penalty imposed by the OCC in history. As part of the settlement, Bank of America acknowledged that it intentionally lacked adequate safeguards and neglected to report suspicious activities, according to the Treasury Department. Bank of America did not adequately address significant warning signs related to questionable customers, including individuals associated with drug trafficking, despite the escalation of concerns by compliance staff, according to the Treasury. Consequently, the bank that handled in excess of $9 trillion in transactions during the previous year neglected to disclose more than $5 billion in questionable activities. Source discovered that Bank of America’s sanctions-screening filter contained a design flaw that hindered its ability to effectively prioritise certain potentially prohibited transactions. Specifically, when a transaction aligned with an individual’s name and date of birth on the US Treasury Department’s sanctions list, the bank’s system failed to categorise the transaction as high priority. The Treasury Department maintains a comprehensive list of thousands of individuals and entities, encompassing terrorists, narcotics traffickers, and companies under sanctions, whose assets may be subject to blocking and who are typically barred from engaging in transactions with US persons or entities.
These breakdowns can undermine US sanctions programs, including the nation’s initiatives regarding Iran and counter-narcotics, as evidenced by the situation with Bank of America, according to findings. Dennis Kelleher stated that the $1.2 billion fine was modest relative to Bank of America’s revenue. “Banks don’t break laws; people do, and until those people – including most importantly executives and supervisors – are personally and meaningfully punished by firings, prosecution, fines and being barred from employment in the industry, these crimes are not going to be stopped,” Kelleher said. Bank of America’s stock fell more than 2.5% in after-hours trading following the announcement of the fine. “The OCC and FinCen are sending a message to BoA and to all banks – if you don’t fix the problem quickly they’ll be a big fine,” said Aaron Klein. “The OCC and FinCen have a lot of penalties they could impose beyond money – they can essentially fire people not just from BoA but from the entire business of banking.” And “Everything the OCC is asking BoA to do to have a stronger anti-money laundering compliance program costs money, reducing the banks’ profit,” Klein added.