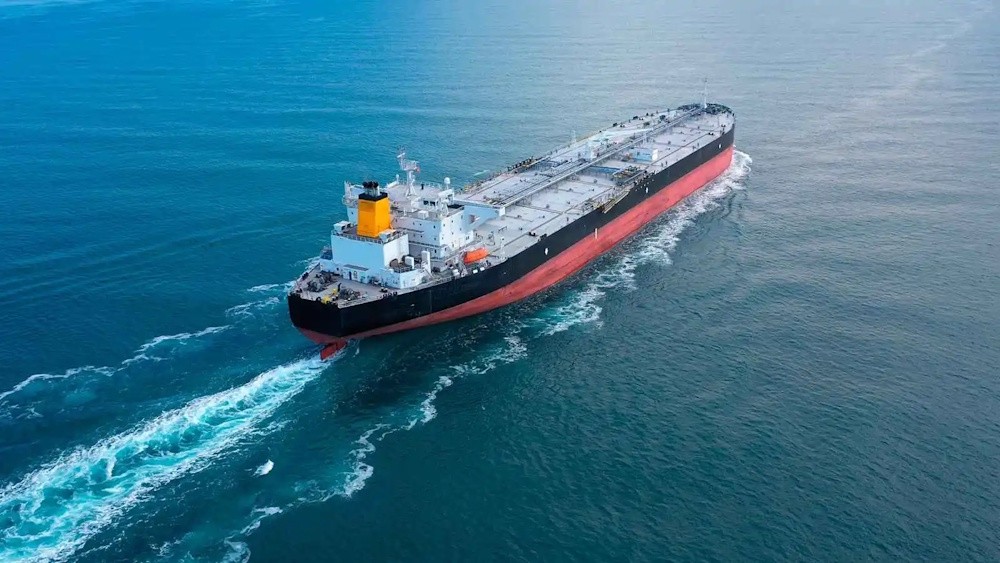
The Iran war has persisted significantly longer than anticipated – and so has a viable oil market. Despite the persistently elevated fuel prices that have incurred nearly $800 in costs for the average US household since the onset of the conflict, crude oil is largely reaching its intended destinations more than six months into the war. That’s because the market has demonstrated notable resilience, by navigating around the Strait of Hormuz with alternative transit routes, relying on substantial crude stockpiles, and reducing global oil consumption. There are legitimate enquiries regarding the sustainability of those conditions and the duration for which they may persist. Some oil analysts suggest that the oil market may sustain this new equilibrium for the foreseeable future, even if the Strait of Hormuz remains in a state that is neither fully open nor completely closed. In that scenario, the Trump administration could theoretically maintain its standoff with Iran for an extended duration. However, there are concerns that the makeshift measures sustaining the oil market may ultimately prove inadequate, potentially leading to a depletion of global inventories to a critical threshold. Energy prices would have no alternative but to rise, potentially compelling the United States to conclude the conflict to avert economic catastrophe. The oil market has navigated the most significant supply shock in history with a resilience that has surpassed many expectations. Oil prices are currently high, yet they have not attained their historical peaks.
There are three reasons for this, as outlined in a research report released last week by Natasha Kaneva. Initially, the market has successfully implemented substantial strategies to circumvent or navigate the Strait of Hormuz. Saudi Arabia has utilised pipelines to redirect several million barrels of oil daily to ports beyond Iran’s reach, although the recent swift advances by Iran’s Houthi allies raise questions about the feasibility of this alternative strategy. The US military has organised a collaborative initiative with Gulf states to facilitate an undercover shuttle operation aimed at transporting oil through the strait. The United States, Venezuela, Brazil, Guyana, and Canada have collectively increased their production by approximately 2 million barrels per day. “Barrels find a way to flow,” stated Kaneva. Second, the majority of nations beyond the United States and China have reduced their oil inventories to a lesser extent than expected, maintaining a reserve of oil that governments can utilise should circumstances deteriorate considerably. Furthermore, global demand for oil has experienced a significant decline during the war, decreasing by approximately 5 million barrels per day. Around the globe, albeit less so in the United States, a significant number of consumers have opted to cancel travel plans, transition to electric vehicles, or utilise bus services instead. Some businesses promoted remote work arrangements for their employees. China is exporting a significant number of electric vehicles, resulting in a strain on global shipping capacity. Additionally, a deficiency in refining capacity across the Middle East, Russia, and China has diminished demand, thereby maintaining a cap on crude prices.
Collectively, these elements contributed to offsetting the approximately 13 million barrels per day that had been diminished as a result of the conflict. According to Kaneva, this new equilibrium has the potential to be maintained for an extended period. The market is operating, though at a relatively elevated price point. JPMorgan does not anticipate a prolonged conflict. However, should that scenario unfold, Kaneva suggests that oil prices are expected to stabilise at approximately $87 per barrel, significantly lower than current figures. If the war concludes, the bank anticipates that oil prices may decline significantly, reaching $64 per barrel. Bob McNally, president and co-founder of Rapidan Energy Group, expresses a more pessimistic outlook. His forecast posits that this situation represents a perpetual conflict – or what he refers to as a “spikey muddle-through” scenario – maintaining Brent at $89 a barrel in the forthcoming year. “We don’t see a full return of Hormuz,” said McNally, who was an energy adviser to President George W. Bush. “A forever war – by jeopardizing the world’s most important supply region – will accelerate the boom in oil and gas prices.” While the oil market has established a new equilibrium, its intricate framework reveals several vulnerabilities that may falter under prolonged scrutiny. The United States and China have depended significantly on their reserves of oil to mitigate the impact of the conflict. They have persisted for a duration that exceeds initial projections. A critical storage facility in Cushing, Oklahoma, reached operational minimums in July, at which point the laws of physics restrict oil companies from efficiently pumping crude through pipelines to transport it to refineries. Yet Cushing’s reserves have shown a modest recovery, inching slightly beyond the danger zone in recent weeks.
China has incrementally raised its oil imports in recent weeks; however, these levels are still millions of barrels per day below pre-war figures. Few outside the Chinese government possess knowledge regarding the exact quantity of oil stored within the country, yet estimates suggest it hovers around a billion barrels. At some unknown point in the future, those inventories will be depleted if the war continues for an extended duration, stated Hamad Hussain, commodities economist at Capital Economics. Such a scenario would lead to a significant disruption in the equilibrium of supply and demand, likely resulting in a substantial increase in oil prices — a prediction that many analysts anticipated at the beginning of the conflict. Sinking inventories likely wouldn’t lead to an immediate price surge; however, they would contribute to increased volatility in oil prices. This scenario may not unfold this year, but it is probable by late next year if current conditions persist, according to Dan Pickering, founder and chief investment officer at Pickering Energy Partners. That is due to the fact that pipeline workarounds cannot be constructed swiftly enough, nor will new supply sources such as Venezuela be able to sufficiently compensate indefinitely, he observed. Another critical element: the sustainability of the US military. “It’s not the hidden hand of the market. It’s the military finding a way,” said Helima Croft. Croft stressed that the might of the US military is not inexhaustible. “Are we forever in the escort service? That’s a heavy lift. These are costly workarounds.”
Croft suspects the war is entrenched in a “grey zone conflict,” characterised by intermittent escalations interspersed with phases of “difficult calm.” She observed that there remains a tangible risk of escalation, reminiscent of the 2019 drone attacks on a Saudi oil field that caused a significant surge in oil prices. One CEO of a major bank remarked that the US-Iran conflict “probably is a forever war.” And “I’m not losing sleep over it, but we should be prepared for that,” the bank CEO said. “A forever war would leave everyone feeling edgy, but after a certain point you realize it’s just the new normal.” US officials and researchers appear to be bracing for that eventuality — or at the very least, a protracted supply disruption. Last week, the US Energy Information Administration determined that oil exports via the Strait of Hormuz will continue to be “constrained” for the remainder of the year. S&P Global Energy has advanced its analysis, indicating in a report that it no longer anticipates a return of Middle East oil production to pre-war levels, even by the conclusion of the upcoming year. “The market is not returning to calm,” said Jim Burkhard, S&P’s global head of crude oil research. “It is adjusting to the new normal defined by unresolved conflict and persistent maritime risk.”