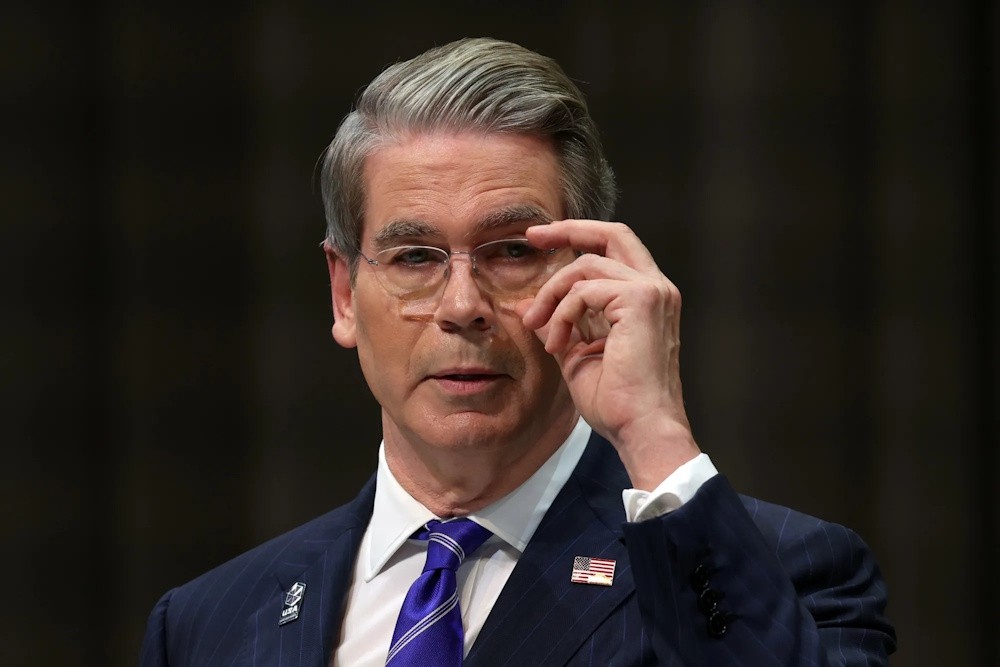
Scott Bessent joined the Trump administration last year equipped with substantial experience in markets, the broad respect of Wall Street, and boundless confidence. Bessent has approached his position as Treasury secretary and President Donald Trump’s chief economic advisor with the same confidence that enabled him to assist George Soros in “breaking” the Bank of England in 1992 by making substantial bets against the pound. The trade compelled the UK to relinquish its attempts to support the currency, resulting in a profit exceeding one billion dollars for Soros. Bessent has recently dared traders to cross him by boldly declaring, “I am the house now.” He’s dismissed criticism by saying if “some of the Bloomberg Terminal bros are unhappy with what I’m doing, well, that’s too bad.” And he’s promised to ease the cost of money by driving down bond yields. However, his attempts to outmanoeuvre the bond market – the most profound and significant market globally – have not met the expectations set by the initial excitement. If anything, critics argue that his efforts have been counterproductive. “The data is clear. He’s added accelerant to the fire. He’s had the exact opposite impact that he wanted,” said Tim Mahedy.
Early last year, Bessent expressed his intention to reduce the crucial 10-year yield to below 4%. Instead, the opposite has occurred, with the benchmark rate momentarily rising above 5.04% on Tuesday for the first time since 2007. With rates rising uncomfortably high last month, Bessent surprised many on Wall Street with a controversial intervention that ultimately tripled Treasury buybacks. However, the plan has proven to be ineffective. Bond yields have risen since Bessent’s intervention, resulting in increased costs for consumers seeking mortgages, small businesses looking for loans, and the federal government attempting to borrow funds. “It massively flopped,” Hardika Singh told. “If anything, this may have made the problem worse. Bessent showed his hand. To investors, it was like, ‘Oh my gosh, he’s worried.’ We should be too.” The Bessent move attracted criticism from his mentor, the renowned investor Stanley Druckenmiller, who authored an op-ed cautioning that attempts to suppress yields would ultimately prove counterproductive. Douglas Holtz-Eakin, a prominent economist during the administration of President George W. Bush, remarked that Bessent’s strategy to manage yields was “doomed to fail” as it overlooked the significant issue at hand: Trillion-dollar deficits stretching into the foreseeable future. “I don’t think you can fool mother nature. You’ve got to fix the fundamentals,” said Holtz-Eakin.
Certainly, the United States was already grappling with a substantial debt burden well prior to Bessent’s assumption of office. Both parties bear responsibility for the budgetary predicament. However, Trump and Bessent committed to addressing that issue, partially by reducing the federal deficit to 3% of GDP. Instead, budget deficits are currently operating at approximately double that level – despite low unemployment and the White House’s assertion that the economy is thriving. “They’ve made it worse. There’s no way around that,” said Holtz-Eakin. David Wessel stated that such intervention in the bond market would be effective only if there is A.) a significant issue in market functionality and B.) it is accompanied by policies designed to address the government budget. “But this isn’t a market-functioning-style emergency. It’s a politically inconvenient increase in yields,” Wessel said. It is inconvenient that as bond yields rise, the American dream becomes increasingly unattainable. Mortgage rates, closely aligned with the 10-year Treasury yield, have reached their peak since June 2025. Undoubtedly, Bessent faces significant challenges as he is compelled to advocate for Trump’s policies, which are often viewed as unpopular and, at times, inflationary.
Last year, his superior initiated a global trade conflict that unsettled the bond market and reversed advancements in inflation. Bessent is credited with persuading Trump last spring to pause those global tariffs, a decision that triggered a significant rally in bonds and particularly in stocks. This year, his boss initiated a military conflict with Iran that continues to intensify America’s cost-of-living challenges and unsettle the bond market. “He’s been taken for a ride by Trump’s chaos policy,” said Access/Macro’s Mahedy. The other issue is that the powers of the Treasury, although extensive, are more constrained than those of the Federal Reserve. Bessent’s bond market intervention seemed to draw inspiration from the Fed’s crisis playbook by establishing a backstop to alleviate market anxieties. That mirrors the actions taken by former Fed chairs Ben Bernanke during the 2008 financial crisis and Jerome Powell in response to the Covid-19 pandemic. “Bessent is trapped by the system. The Fed can just hit the ‘M’ button on the keyboard and create money out of thin air,” said Mahedy.
“But Treasury doesn’t have that same power to create money. Bessent’s got to find it and what he’s promised are drops in the bucket.” Ed Yardeni notes that the $6 billion in buybacks Bessent has promised are “little more than a rounding error” in the $32 trillion Treasury market. “The Bond Vigilantes are daring Bessent to use the bazooka in his toolkit,” Yardeni wrote in a note to clients last week. Even as the bond markets have shifted unfavourably, Bessent has maintained his characteristic confidence. Last week, Bessent justified his actions in the Japanese currency market by cautioning traders that he possesses information they lack. “I have asymmetric information… You can bet against me if you want,” he said at a fireside chat at Southern Methodist University. Holtz-Eakin expressed surprise at Bessent’s brash comments. “It’s unwise. He’s been on the other side. He broke the pound. You don’t bait people like that. It’s not a good move,” he said.